What is wealth management? It is a coordinated approach to helping individuals, families, and business owners organize, manage, protect, and plan for the transfer of financial assets over time, depending on the customer’s goals, financial circumstances, risk tolerance, and the services selected. Many people think wealth management is only for the ultra-wealthy. In practice, it may help customers who want more structure around investments, retirement, estate planning, risk management, and long-term financial decisions.
Wealth management is not one product. It is an ongoing advisory relationship that connects several parts of a customer’s financial life. That may include investment management services, estate planning services, retirement income strategy, insurance review, tax coordination, and legacy planning.
Springs Valley’s Financial Advisory Group brings personalized wealth management strategies to individuals, families, and business owners across Indiana and the rural Midwest. The team helps customers review financial goals, understand the differences between planning options, and build strategies that fit their stage of life, financial circumstances, and risk tolerance.
Investment and advisory services are not deposits; not insured by the FDIC; not a deposit or other obligation of, or guaranteed by, Springs Valley Bank & Trust Company; not insured by any federal government agency; and may lose value, including possible loss of principal. This disclosure applies to all investment, advisory, insurance, retirement, education funding, and wealth management examples discussed in this article, as applicable.
This guide covers:
- What is wealth management?
- How does wealth management work?
- Wealth management vs. financial planning.
- Wealth management services explained.
- Who needs wealth management?
- How to choose a wealth manager.
- Wealth management strategies for families.
- Working with Springs Valley financial advisors.
This content is provided for general informational and educational purposes only and should not be considered individualized financial, investment, tax, or legal advice. The information presented does not take into account the specific financial circumstances, objectives, or risk tolerance of any individual. Customers should consult their financial, tax, legal, and other professional advisors before making decisions based on their individual circumstances.
What is Wealth Management?
Wealth management is a broad financial service that combines advice, planning, and investment oversight. It often includes retirement, estate, tax, insurance, and portfolio considerations.
The goal is to help customers make connected financial decisions rather than treating each account or goal separately.
Definition and Core Purpose
The core purpose of wealth management is to help customers align financial assets with long-term goals.
A customer may want to prepare for retirement, pass assets to family, support a business transition, fund education, reduce financial risk, or plan charitable giving. Wealth management brings these priorities into one coordinated strategy.
That coordination matters. Investment decisions can affect tax planning. Estate planning can affect family wealth transfer. Retirement withdrawals can affect long-term income. A wealth manager helps connect those pieces.
The History and Evolution of Wealth Management
Wealth management has changed over time. It once focused mostly on investment portfolios for affluent households. Today, it often includes broader planning conversations for families, retirees, business owners, and professionals with growing financial complexity.
The service has also become more collaborative. A wealth advisor may coordinate with attorneys, accountants, trust officers, insurance professionals, and other specialists.
That does not mean every customer needs the same level of service. It means wealth management can scale based on the customer’s needs.
Key Players: Advisors, Planners, and Managers
Several professionals may be involved in wealth management.
A financial advisor may help customers review goals, investments, and planning needs. A financial planner may focus on budgeting, retirement, education funding, insurance, and goal-based planning. An investment manager may focus on portfolio construction, risk, and asset allocation.
Some customers also work with estate attorneys, tax professionals, trustees, or business advisors.
The best structure depends on the customer’s financial situation and the services needed.
How Does Wealth Management Work?
Wealth management usually begins with a discovery process. The advisor needs to understand the customer’s full financial picture before giving meaningful guidance.
That includes assets, debts, income, expenses, risk tolerance, family needs, business interests, retirement goals, estate plans, and personal priorities.
The Client Discovery and Onboarding Process
Discovery is the foundation of a wealth strategy.
An advisor may ask about:
- Current accounts and investments
- Retirement savings
- Income sources
- Insurance coverage
- Debts and liabilities
- Business ownership
- Estate documents
- Family goals
- Risk tolerance
- Expected life transitions
This process helps the advisor understand what the customer wants to accomplish and what needs attention.
Creating a Personalized Wealth Strategy
After discovery, the advisor can help build a personalized strategy.
That strategy may include investment allocation, retirement income planning, estate planning coordination, beneficiary review, insurance needs, and tax-aware considerations, in coordination with the customer’s tax professional.
The strategy should be specific enough to guide action but flexible enough to change as life changes. A plan for a new business owner may look different from a plan for a retiree, a growing family, or someone receiving an inheritance.
Ongoing Review and Portfolio Rebalancing
Wealth management is ongoing. Markets change. Family needs change. Tax rules may change. Goals may also shift over time.
Portfolio rebalancing is one common part of ongoing review. Rebalancing means adjusting a portfolio back toward its intended mix when market movement changes the allocation.
Customers should ask how often reviews happen, what triggers changes, and how the advisor communicates updates.
Wealth Management Services Explained
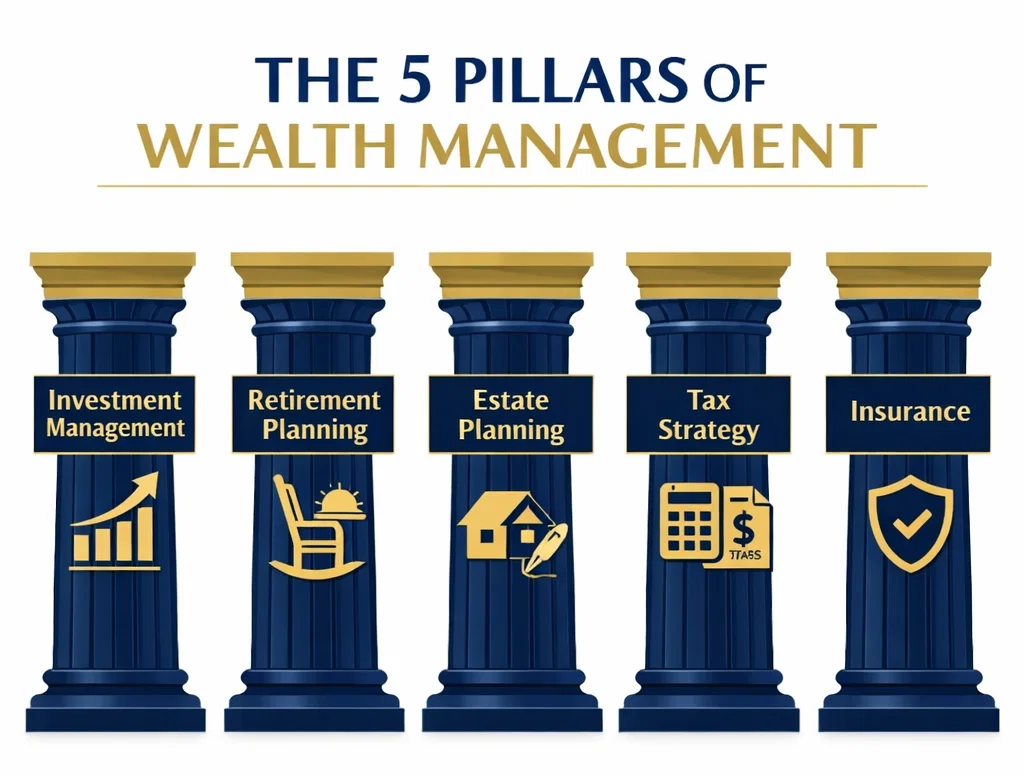
Wealth management services vary by firm and advisor. Customers should ask which services are included, which are separate, and which outside professionals may need to be involved.
A strong wealth management relationship should make the customer’s financial picture easier to understand.
Investment Management and Portfolio Strategy
Investment management services may help customers build and maintain portfolios intended to align with goals, risk tolerance, and time horizon, subject to market risk and the terms of the applicable account agreement.
This may include asset allocation, portfolio review, diversification, rebalancing, and investment selection.
No investment strategy can guarantee returns or prevent losses. Customers should understand risk before investing.
Investment and advisory services are not deposits; not insured by the FDIC; not a deposit or other obligation of, or guaranteed by, Springs Valley Bank & Trust Company; not insured by any Federal Government Agency; and may lose value, including possible loss of principal.
Retirement Planning and Income Strategy
Retirement planning focuses on preparing for life after regular employment income changes or ends.
A retirement income strategy may review Social Security timing, pension options, investment withdrawals, required minimum distributions, and cash flow needs.
The goal is to help customers understand how different income sources may work together.
Estate Planning and Trust Services
Estate planning services help customers plan how assets may be managed and distributed.
This may include beneficiary review, wills, trusts, powers of attorney, health care directives, and legacy planning. Attorneys usually prepare legal estate documents.
Trust services may help with asset management, administration, or long-term distribution instructions, depending on the customer’s needs.
Tax Strategy and Coordination
Tax strategy is an important part of wealth management, but financial advisors do not replace a customer’s tax professional.
A wealth advisor may coordinate with a tax advisor to review tax-aware investment strategies, retirement account distributions, charitable giving, or business transition planning.
Customers should consult their own tax advisors before making tax decisions.
Insurance and Risk Management
Insurance products may help address certain risks within a financial plan, depending on the product, coverage, exclusions, costs, underwriting, and the customer’s needs. A wealth review may include life insurance, disability insurance, long-term care planning, liability exposure, and business insurance needs.
The goal is not to buy more coverage automatically. The goal is to review whether current coverage fits the customer’s family, assets, debts, and future plans.
Who Needs Wealth Management?
Who needs wealth management? The answer depends on financial complexity, goals, and the need for coordinated advice.
Wealth management may be helpful for customers who want help making several financial decisions work together.
High-Net-Worth Individuals and Families
High-net-worth individuals and families may need help managing investments, estate planning, charitable giving, taxes, family governance, and legacy goals.
Complexity can grow as assets grow. Multiple accounts, properties, business interests, and family needs can make decisions harder to manage alone.
A wealth manager may help organize the financial picture and coordinate next steps with the customer’s other professionals.
Business Owners Planning for Exit or Succession
Business owners often have wealth tied to the business. That can make planning more complex.
They may need help with succession planning, retirement income, business valuation, tax coordination, key person risk, and estate planning.
Retirees Managing Distributions and Legacy
Retirees may need help turning savings into income. They may also want to protect assets, support family, give to charity, or plan estate distribution.
A wealth advisor can help review retirement income strategy and legacy goals, but investment outcomes, income needs, tax results, and estate outcomes are not guaranteed.
This type of planning should account for investment risk, health care needs, tax considerations, family needs, and changing expenses.
How to Choose a Wealth Manager
How to choose a wealth manager is an important decision. Customers should look for experience, clear communication, transparent fees, and a planning approach that fits their needs.
A good advisor should explain complex topics in plain language.
Credentials and Fiduciary Standards to Look For
Credentials can help customers understand an advisor’s training and professional standards.
Common designations include CFP® (Certified Financial Planner) professional, CTFA (Certified Trust and Financial Advisor), and CPA (Certified Public Accountant). The CFP® Board says CFP® professionals must act as fiduciaries when providing financial advice, which means they must act in the client’s best interests under CFP® Board standards.
Investment advisers also have fiduciary obligations under federal law. The SEC (Securities and Exchange Commission) says investment advisers must provide advice in the client’s best interest and make full and fair disclosure of conflicts of interest.
Customers should still ask each advisor what standard applies, what services are included, and how conflicts are handled.
Questions to Ask Before You Hire
Before choosing a wealth manager, customers should ask:
- What services are included?
- What types of clients does the advisor usually serve?
- How is the advisor paid?
- What credentials does the advisor hold?
- Is the advisor acting as a fiduciary?
- How often are reviews scheduled?
- How are investment decisions made?
- What happens if the customer’s goals change?
The FINRA (Financial Industry Regulatory Authority) suggests asking investment professionals how they get paid, including whether they receive commissions, charge an asset-based fee, charge a flat or hourly fee, or use another method.
Fee Structures: AUM (Assets Under Management), Flat Fee, and Commission
Wealth management fees vary. Customers should review the fee structure before agreeing to work with an advisor.
Common structures may include assets-under-management fees, flat fees, hourly fees, planning fees, commissions, or a combination.
Advisory fees may be based on the size of a portfolio, often called an assets-under-management or asset-based fee. Fees and compensation vary by advisor, account type, services selected, and applicable agreement. Customers should request and review written fee and compensation disclosures before opening an account or engaging services.
The lowest fee is not always the best fit. Customers should compare cost, services, communication, conflicts of interest, and whether the services offered match the customer’s needs and objectives.
Wealth Management Strategies for Families
Wealth management strategies for families often focus on long-term stability, education, estate planning, and generational transfer.
The goal is to help family members understand how money will be managed, protected, and passed on.
Generational Wealth Planning
Generational wealth planning helps families think beyond one person’s lifetime.
That may include estate planning, trust planning, beneficiary review, charitable goals, business transition planning, and family communication.
A clear plan can reduce confusion and help family members understand roles, responsibilities, and expectations.
Education Funding and 529 Plans
Education funding can be part of a family wealth strategy. A 529 plan may help families save for qualified education expenses, subject to plan rules, investment risk, fees, tax rules, and the customer’s individual circumstances.
Customers should review plan rules, tax considerations, investment options, fees, ownership details, and potential impacts on financial aid or other planning goals before opening or contributing to an education account.
A financial advisor can help families compare education funding with other goals, such as retirement savings and emergency reserves.
Family Trusts and Estate Distribution
Family trusts may help manage how assets are distributed. They may also support privacy, continuity, and planning for minors or family members who need support.
Trusts are legal tools. Customers should work with an attorney to decide whether a trust is appropriate.
A wealth advisor can coordinate with the attorney and help align trust assets with the broader financial plan.
Working With Springs Valley Financial Advisors
Springs Valley’s Financial Advisory Group helps customers review long-term financial needs with local service and practical guidance.
The goal is not to force a standard plan. It is to help customers understand options and build a strategy that reflects their goals.
The Financial Advisory Group Difference
The Financial Advisory Group understands the needs of rural Indiana families, business owners, farmers, retirees, and professionals.
Customers may want help planning retirement, managing investments, building a legacy, or coordinating several financial decisions. Springs Valley brings personal service to those conversations.
That local relationship can make planning feel more connected to real life.
How to Schedule Your First Consultation
Customers can contact Springs Valley Bank & Trust to ask about scheduling an introductory conversation with the Financial Advisory Group.
The first conversation may cover goals, current accounts, planning concerns, and next steps. Customers should bring questions, recent statements, estate document summaries when available, insurance details, and retirement account information.
Springs Valley can help customers understand which services may fit their needs.
FAQs
This content is provided for general informational and educational purposes only and should not be considered individualized financial, investment, tax, or legal advice. The information presented does not take into account the specific financial circumstances, objectives, or risk tolerance of any individual.
Investment and advisory services are not deposits; not insured by the FDIC; not a deposit or other obligation of, or guaranteed by, Springs Valley Bank & Trust Company; not insured by any Federal Government Agency; and may lose value, including possible loss of principal.
What Is Wealth Management, and How Is It Different From Financial Planning?
Wealth management is a coordinated service that may include investment management, retirement income planning, estate planning coordination, tax strategy, and risk management.
Financial planning may focus on specific goals such as saving, budgeting, retirement preparation, or education funding. Wealth management is broader and often supports customers with more complex financial needs.
Who Needs Wealth Management Services?
Wealth management services may help high-net-worth individuals, business owners, retirees, families, and customers with several connected financial goals.
It can be useful when investments, retirement planning, estate planning, tax coordination, and family needs should be reviewed together.
What Services Are Included in Wealth Management?
Wealth management may include investment portfolio management, retirement income planning, estate planning coordination, tax-aware strategy, insurance review, education funding, business planning, and legacy planning.
Services vary by advisor and firm. Customers should ask what is included, what is excluded, what fees apply, what conflicts may exist, and what disclosures or agreements will govern the relationship before starting.
How Do I Choose a Wealth Manager?
Customers should look for clear communication, relevant experience, transparent fees, and appropriate credentials.
They should also ask whether the advisor acts as a fiduciary, how investment decisions are made, how often reviews happen, and how the advisor is paid.
What is a Fiduciary Financial Advisor?
A fiduciary financial advisor is required to act in the client’s best interest when providing advice within the scope of the fiduciary relationship and under the standard that applies to that advisor.
The SEC says investment advisers owe fiduciary duties that include a duty of care and a duty of loyalty. This includes providing advice in the client’s best interest and disclosing conflicts of interest.
Fiduciary obligations apply only within the scope of the professional’s advisory engagement. Customers should request written information about the services, fees, conflicts of interest, and applicable standard of care before opening an account or engaging services.
How Much Does Wealth Management Cost?
Wealth management costs vary by advisor, service level, portfolio size, account type, and fee structure.
Fees may be based on assets under management, a flat fee, an hourly fee, commissions, planning fees, or a combination. Customers should ask for a clear written explanation of all costs, fees, compensation arrangements, and potential conflicts of interest before agreeing to services.
Can Families Benefit From Wealth Management?
Yes. Families may benefit from wealth management when they want help with estate planning, education funding, family trusts, investment coordination, retirement planning, and generational wealth transfer.
A family strategy can help clarify goals and reduce confusion across generations, but outcomes depend on the family’s circumstances, legal documents, market conditions, tax considerations, and implementation.
When Should I Start Working With a Wealth Manager?
Customers often start working with a wealth manager during major life transitions. These may include approaching retirement, receiving an inheritance, selling a business, buying or selling property, changing careers, or planning a legacy.
Starting earlier may give customers more time to organize accounts, review risks, and consider how financial decisions align with long-term goals.
What is wealth management? It is a coordinated way to manage investments, retirement planning, estate planning, risk, and long-term financial goals. It can help customers move from scattered decisions to a clearer strategy. Springs Valley Bank & Trust offers wealth management services and financial advisory services for customers who want local guidance and a practical planning relationship. Customers can contact Springs Valley Bank & Trust or visit any Springs Valley branch to ask about scheduling a consultation. Investment and advisory services are not deposits; are not FDIC insured; are not guaranteed by Springs Valley Bank & Trust Company or any federal government agency; and may lose value, including possible loss of principal.